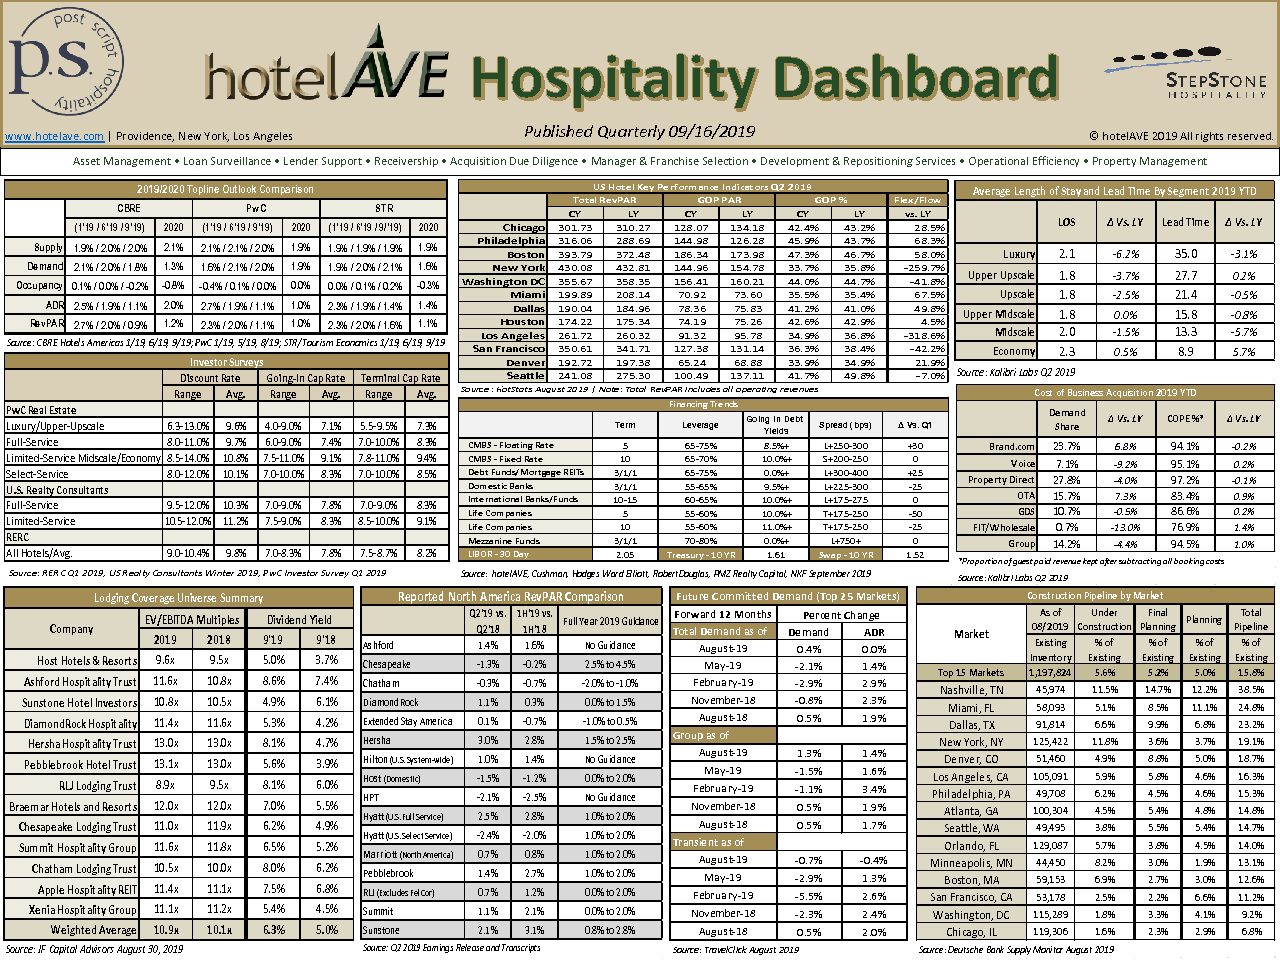
Our hotelAVE Hospitality Dashboard 3Q26 is now available!
-
-
-
- CoStar, HVS, and PWC raised their 2026 YE RevPAR forecasts to 4.4%-5.6%. For 2027, CoStar and HVS are forecasting more conservative RevPAR growth of 2.1% and 2.7%, respectively.
- Solid 3Q26 RevPAR gains of 9.3% drove increases in GOPPAR of 10.7% versus STLY. Hotel REIT’s (weighted towards luxury and upper upscale) reported 3Q26 RevPAR increases of 7.2%-12.5% and EBITDA growth of 14.4%-29.5%, far exceeding lower chain scales.
- Implied hotel REIT cap rates are lower than STLY driven by strong price appreciation. Wall Street is rewarding not only fundamentals, but the upper-upscale and luxury portfolio profile.
- Lending spreads have remained largely unchanged since last quarter despite an increase in benchmark SOFR and Treasury rates. The SOFR forward curve suggests more rate hikes ahead, putting more pressure on debt service coverage and terms for refinancing and acquisitions.
- Rooms under construction in Top 25 markets grew to 2.6% of existing inventory since last quarter, above long-term industry average of 1.7%. New supply growth is highest in New York, Detroit and select Sun Belt markets.
- Shadow supply decreased in most markets over the last year however it makes up 12.2%-44.1% of hotel keys in top markets. Stricter municipal regulations and bans, increased operating costs and taxes, and more stringent HOA restrictions are eroding profit margins and driving properties back into the long term rental market.
-
-
Download the full summary to stay up-to-date: hotelAVE Hospitality Dashboard 3Q26